Business Clinic: Should we sell solar lease income for lump sum?
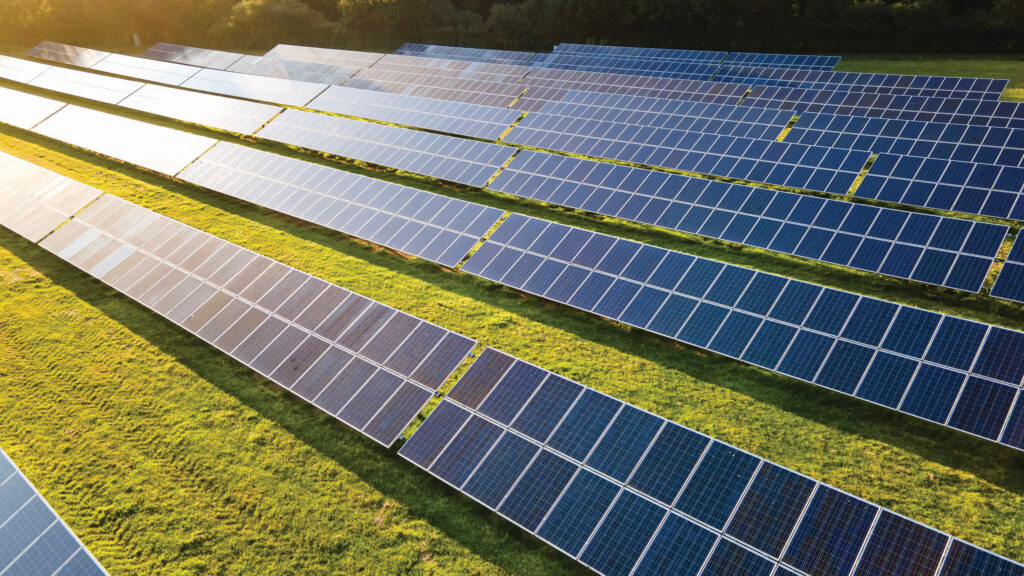 © AdobeStock
Whether it’s a legal, tax, finance or management question, Farmers Weekly’s expert panel can help.
Here, Carter Jonas associate Will Hunt of the firm’s mergers and acquisitions department, gives advice on how to consider an offer to capitalise the anticipated future rental income on along term solar lease.
See also: Business Clinic: how do we negotiate partial surrender of an AHA tenancy
About the author
 William Hunt is an energy specialist in Carter Jonas’ energy infrastructure team, focusing on mergers and acquisitions advice, valuation and financial modelling.
He works with developers, landowners and investors to help structure and execute energy infrastructure transactions.
He is based at Carter Jonas’ London headquarters.
Q: We signed a solar lease on just over 32ha of our 243ha farm about five years ago. The income is coming in with no problem, but we have been approached by a company offering to capitalise our expected lease income over the remaining 20 years into an upfront lump sum. It sounds tempting but we have a lot of questions.
For example, we get a top-up payment when the energy produced by the project is above a certain level – this is almost impossible to predict, so should this element be left out of any capitalised calculation?
Also, many solar projects are being extended beyond their initial term – how should the possibility of this be treated, or should any proposal just stick to the original 25-year lease? How do we judge whether what they are offering is appropriate in what we understand is a fast-developing investment market?
A: Over the past year large real estate and infrastructure investors, including pension-backed funds, have begun targeting UK renewable energy ground leases.
They are attracted by the same characteristics that have drawn institutional capital to sectors like student accommodation and social housing for many years: long-term, inflation-linked, secured income streams.
As a result, renewable energy leases are increasingly being recognised as an investment class in their own right, creating a deeper and more competitive market.
What might previously have been viewed simply as a source of annual rental income is now attracting serious interest from investors seeking long-term returns, which is why offers like this are starting to land on landowners’ desks.
A rental income strip, as this is termed, allows a landowner to convert some or all of the remaining rent under a lease into an upfront lump sum, while retaining ownership of the underlying land.
For some, this may provide greater flexibility around succession planning, debt reduction, reinvestment or wider family wealth planning. It is not a replacement for those discussions, but potentially another tool to consider alongside them.
Range of offers
Approaches vary by investor. Some will look to forecast energy production alongside power price forecasts, allowing them to assess in which periods the revenue share mechanism is likely to exceed the base payment, and reflect that in their price – assuming the lease contains such a mechanism.
Others will leave the revenue share element out of the capitalised price entirely, allowing the landowner to retain it.
What matters most is that an offer clearly sets out what is and is not included, so the landowner knows exactly what they are selling and what they are keeping.
The possibility that a solar project could be extended beyond its initial term can also be approached in different ways.
Some investors will factor potential extension periods into the price offered, though typically applying a higher discount rate to cashflows falling within the extension period, reflecting the greater uncertainty over whether they will arise.
Others will only model the guaranteed lease term and only bring extension periods into their pricing once they are confirmed.
Again, what matters most is that any offer is transparent about which approach has been taken.
At Carter Jonas, we are working with several landowners considering potential income strip/leasehold sales, and we offer free, indicative valuation advice to help assess whether a bid from an investor is competitive.
IHT planning
There is a further reason to revisit this now: changes to inheritance tax relief from April 2026 are prompting many landowners to review wider estate and succession planning arrangements.
Land subject to a renewable lease will often require separate consideration, making it sensible to assess how these assets and income streams fit within broader family and business objectives.
The tax treatment of any transaction will depend on individual circumstances and the structure adopted, so landowners should seek advice from their own tax adviser before proceeding.
Do you have a question for the panel?
Outline your legal, tax, finance, insurance or farm management question in no more than 350 words and Farmers Weekly will put it to a member of the panel. Please give as much information as possible.
Email your question to FW-Businessclinic@markallengroup.com using the subject line “Business Clinic”.