Wheat rally loses momentum as global supply outlook improves
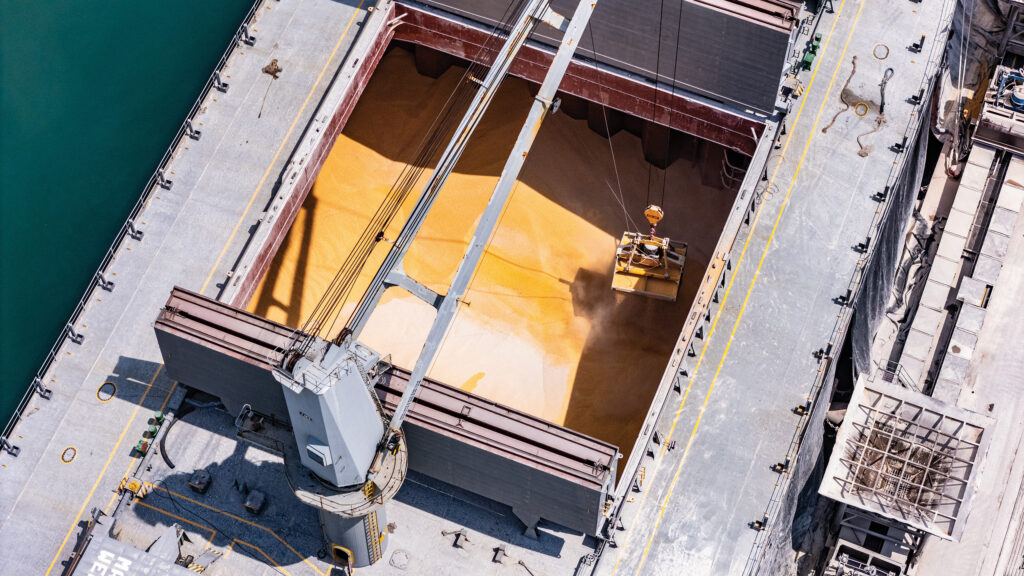 © AdobeStock
A more comfortable global wheat supply outlook, combined with prospects of better access to Black Sea grain, has led to an easing of UK wheat values from recent highs.
The downturn was triggered by the latest USDA World Agricultural Supply and Demand Estimates report, published on Friday (11 September).
See also: Find all our market prices in one place
That report raised global supply projections by 3.5m tonnes to 1.103bn tonnes, mainly due to higher production by major exporting countries.
Australia’s production rose by 3m tonnes to 31m tonnes and Canada’s increased by 1m tonnes to 36m tonnes.
At the same time, Ukraine’s crop was raised by 0.6m tonnes to 26m tonnes following a record yield as harvest nears completion.
The increases more than offset a 1m tonne reduction in Kazakhstan’s crop, to 15m tonnes, while global ending stocks for 2026-27 were raised by 3m tonnes to 276.3m tonnes.
“Australia’s crop has been better than expected, and the strong El Niño hasn’t really affected it yet; they have seen some decent rain,” said Arron Mayhew, head of conventional trading at Saxon Ag.
“The crops aren’t record-breaking, but they are bigger than expected.”
November 2026 London wheat futures, which were trading at a high of £219.25/t earlier this month, closed at £209.25/t on Tuesday 15 September.
Black Sea situation
According to Mr Mayhew, this could still be artificially high as ongoing disruption to exports through the Black Sea continues to offer some support to wheat prices.
“In general, there is enough wheat in the world, so we’re at prices which are inflated against what the supply and demand picture actually is,” he said.
“The biggest problem is access to that wheat, as it’s being held against a big wall in Ukraine and Russia, so it’s a logistics market as much as anything else.”
Traders are certainly watching closely for signs that exports could improve.
Claims by US president Donald Trump on Monday (14 September) that Russia and Ukraine had agreed to stop attacking each other’s energy infrastructure raised hopes of progress towards improved access to Black Sea grain and led to a softer market.
But continued attacks on energy facilities by both sides on Tuesday (15 September) shored up prices once again.
“The market is very nervy on the back of any news; it’s very reactive to very little,” said Rob Hess, senior trader at GrainLink.
Domestic market
Closer to home, the smaller UK wheat crop continues to provide some support to prices, with the AHDB estimating that yields are 12% down on the five-year average.
This comes against a backdrop of tight domestic wheat stocks in England and Wales, estimated at 351,000t, down 46% on June 2025, and the lowest level for June since 2000, according to AHDB analysis.
“Demand has been high recently, due to the dry weather – feed mills have been busy because there has just been no grass,” said Mr Hess.
Despite this, ex-farm prices were a touch softer mid-week, with the Farmers Weekly average feed wheat price sitting at £203.10/t on Wednesday 16 September – down £2.20/t on the previous week.
Milling grade material is earning a smaller premium than it did a year ago, according to the AHDB.
Delivered values for bread wheat are quoted at about a £16/t premium to the November futures value, whereas 12 months ago, that differential was £25/t.