
Wheat prices fall as global supply weighs on markets
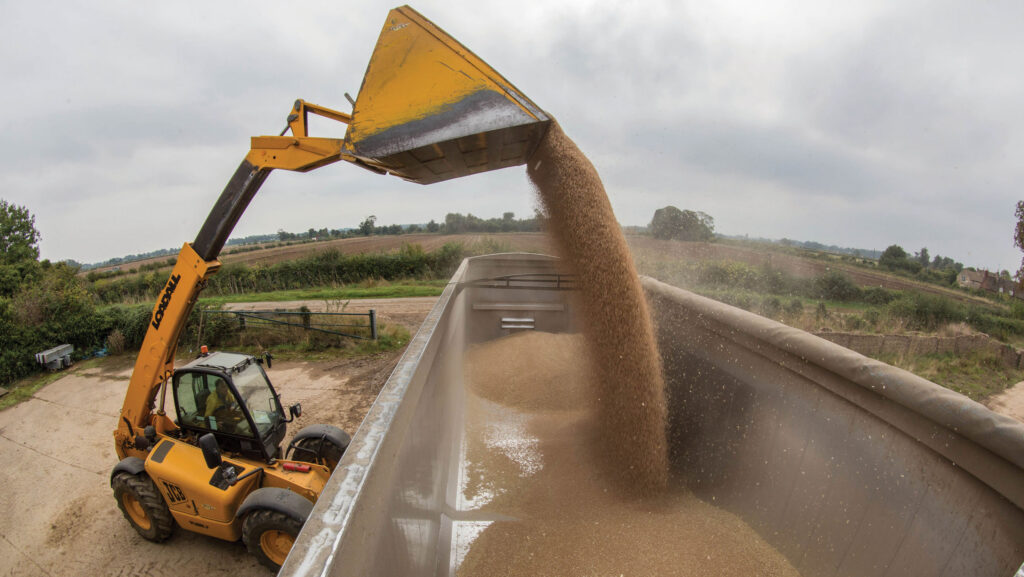 © Tim Scrivener
UK wheat prices have come under pressure from improving global supply prospects and hopes of progress in Russia-Ukraine peace talks, although renewed Black Sea disruption has limited the downside.
London feed wheat futures fell by £11.25/t over the week to close at £193.75/t on Friday 23 October, according to the AHDB, as global grain markets weakened.
The sell-off followed reports of renewed peace talks, raising the prospect of Black Sea grain exports recovering. However, conflict continues and uncertainty remains over how quickly damaged port infrastructure could be repaired.
See also: Wheat rally loses momentum as global supply outlook improves
Larger harvests in the southern hemisphere have also weighed on prices. Argentina’s Rosario Stock Exchange raised its forecast for the 2026-27 wheat crop to 23.8m tonnes, from 21m tonnes previously, while favourable weather has helped US winter wheat planting and maize harvesting progress.
Nearby Chicago wheat futures fell by 6.5% last week, while Paris milling wheat dropped 4%.
However, prices showed signs of stabilising on Tuesday 27 October. Paris wheat rebounded from a three-month low amid buying interest from Jordan and a tender from Tunisia, while Chicago wheat’s decline slowed as technical indicators pointed to an oversold market.
Farm selling remains quiet
Despite the decline in futures, physical trading in the UK has been subdued, with growers reluctant to sell at current levels and consumers taking additional cover where they have forward sales to fulfil.
Steve Atha, trading manager at Wynnstay, said: “We have seen a lack of farm selling this week and last, while consumers are looking to take additional cover because prices have come down.”
However, he said there was enough wheat in the system to meet demand for now, with procurement activity and farm-gate cash buying particularly quiet.
“Millers’ demand is lacklustre at best, and consumers are covering business they’re writing, but leaving anything else alone,” he said.
Premiums over futures had narrowed slightly, particularly for feed wheat, with a smaller reduction for milling wheat.
Mr Atha said he expected the market could be due a correction, potentially bringing a bounce in November or December as manufacturers’ demand increased. However, he added that global supply, political developments and the UK Budget all added uncertainty.
As Farmers Weekly went to press on Wednesday (28 October) ex-farm feed wheat was quoted at £198.8/t, with milling grade attracting a premium of about £12.50/t.
UK balance sheet tightens
The AHDB’s early balance sheet for 2026-27 points to tighter domestic supplies, despite a small increase in production.
Total wheat availability is forecast at 16.34m tonnes, down 215,000t year-on-year. Opening stocks are estimated at 1.51m tonnes, 24% lower than last season, while production is expected to rise 1% to 12.07m tonnes. However, output remains 9% below the five-year average, partly reflecting dry conditions in southern England.
Imports are forecast to increase to 2.75m tonnes, as lower opening stocks increase the need for imported feed grain.
Domestic consumption is expected to fall by 124,000t to 13.98m tonnes, largely because of weaker flour milling and bioethanol demand, while animal feed consumption is forecast to remain broadly stable.
The supply-demand balance is projected to fall by 91,000t to 2.36m tonnes, leaving 859,000t available for export or free stocks after allowing for operating requirements.
While tighter UK supplies could offer some underlying price support, global market movements and domestic demand will remain key influences in the months ahead.